- /
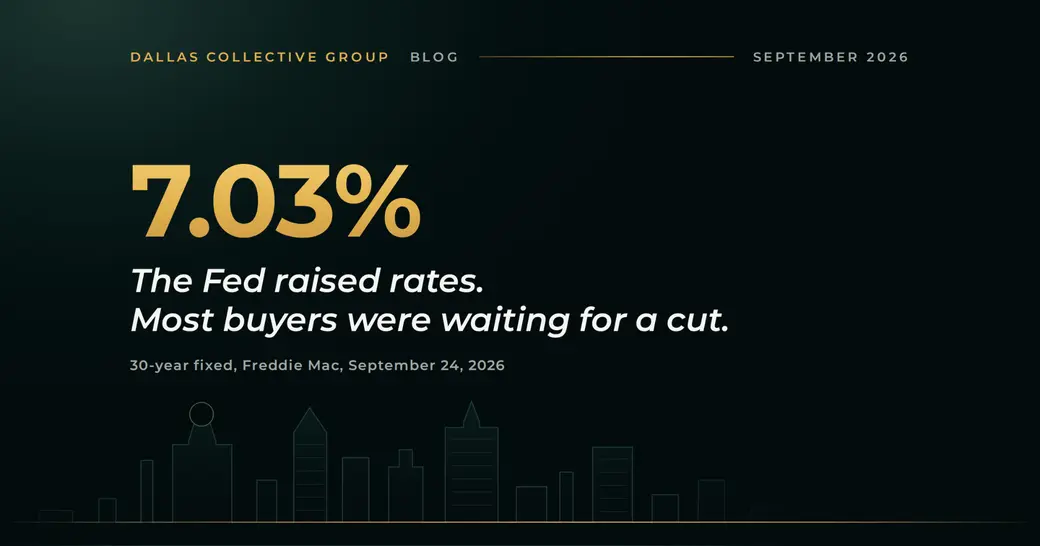
The Fed raised rates. 72% of buyers were waiting for a cut.
On September 16 the Federal Reserve raised its benchmark rate by a quarter point, to a range of 3.75% to 4%. The vote was unanimous. The statement said inflation is still elevated and that the move would support "a timelier return" to the 2% goal. The Fed's own projections put the rate at 4.1% at the end of 2026 and again at the end of 2027. Read plainly, that means no cut is on their map for more than a year.
Mortgage rates didn't wait for the meeting, and they didn't stop after it. Freddie Mac's weekly average went from 6.95% to 7.03% the week of September 24. A year ago that number was 6.30%. Mortgage News Daily, which tracks what lenders are actually quoting each day, had the 30-year at 7.43% on September 25 after touching 7.45% the day before.
Now the other number. In a Neighbors Bank survey of 1,000 prospective buyers fielded in July, 72% said they had paused their home search waiting for lower rates. More than half were waiting for something around 5%, a rate last seen in August 2022. Only 35% could name the current 30-year range. They'd been waiting 13 months on average, and 41% already regretted it. That was in July, when rates were in the sixes.
I'm not sharing that to talk anyone into buying. I'm sharing it because a plan built on a number nobody can name is not a plan.
Why the Fed's rate and your rate aren't the same thing
Mortgage rates don't follow the Fed's rate directly. They follow the 10-year Treasury, and the 10-year moves on inflation expectations. When the Fed says inflation is sticky enough to justify a hike, the bond market prices in a longer fight, and mortgage rates rise before the Fed ever touches anything. That's what happened through late August and September. The hike confirmed it. It didn't cause it.
Here's a detail most people miss. Freddie Mac's widely quoted survey is a weekly average and it lags. The daily number a buyer gets quoted this week is 40 basis points higher than the headline. If someone tells you rates are "about 7," ask them what day that was.
What I'm telling people who are waiting
The same thing I told them in August, when it was cheaper. You can always refi to a better rate. You can never change what you paid for a house.
The buyers who paused in July to wait for 5% are now looking at 7.4%. The house didn't get cheaper while they waited. In DFW the median sale price is down 0.2% year over year, which is flat, and inventory is tighter than it was a year ago. What changed is the payment, and the payment is the part you can fix later.
So the decision isn't "wait for a cut." The decision is whether the house, the payment, and the plan work at the rate that exists today. If they work, buy the house and treat the rate as a lease you'll renegotiate when the market lets you. If they don't work at today's rate, waiting is right, and no amount of Fed speculation changes that either.
If you want to run your numbers at today's rate instead of the one you're hoping for, that's a conversation I'm happy to have.
Categories
Josh Waters